
Milky Mist IPO - Any Cream Left for Investors?
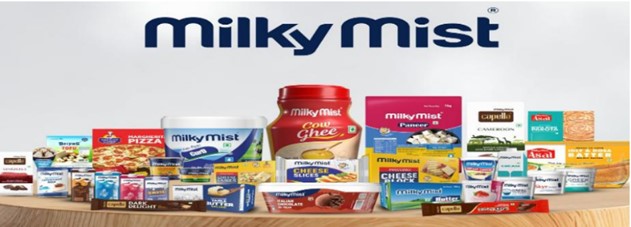
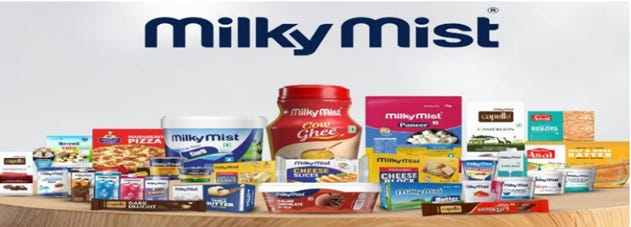
Milky Mist Dairy Food Ltd is a South India-founded, premium value-added dairy products (VADP) company, notably not a traditional liquid/pouch milk player. Started in the 1980s as a milk trading business and pivoted into paneer manufacturing in 1993, it has grown into India’s largest paneer producer (190 tons/day) and largest Greek yogurt producer, with a full portfolio spanning paneer, cheese, curd, yogurt, ice cream, ghee/butter, and long-life dairy products essentially “breakfast to dinner table.” It’s headquartered in South India (~70% of revenue) but expanding nationally, growing revenue at roughly a 30%+ CAGR, with industry-leading EBITDA margins (~14%) and premium per-liter realizations.
IPO Details:
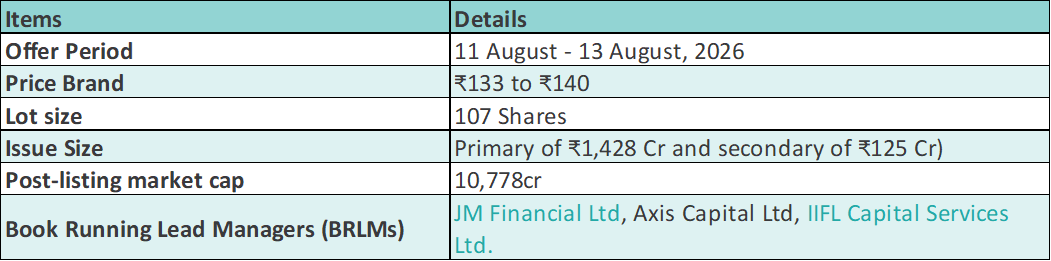
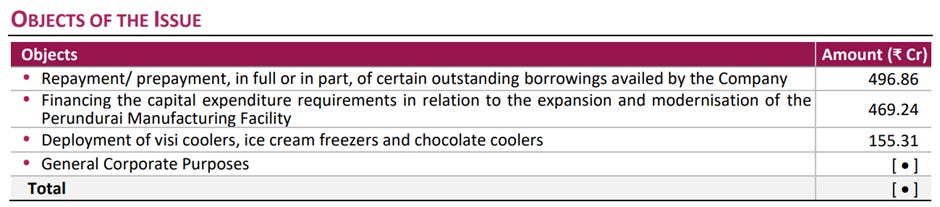
The fresh issue will be primarily used to finance greenfield capex in its solitary mega unit at Perundurai.
Key Investment Highlights:
Market Leadership in Value-Added Dairy Products:
Milky Mist is the closest any brand has come to competing with the Big Daddy of Indian dairy industry AMUL (A cooperative society based in Gujarat) on products like Paneer and Cheese, making it the largest private-branded paneer player in India with a 19% market share and in cheese (~12% market share in South India, ~5% market share nationally), yogurt (~13% nationally amongst private players) and curd categories, particularly in South India.
Wide Distribution Reach and Multi-Channel Presence:
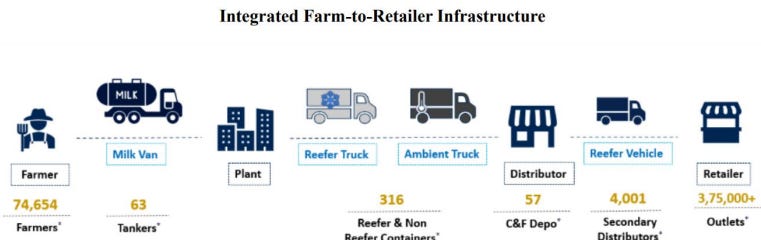
Milky Mist has established an extensive distribution network comprising over 4,000 distributors, more than 3.75 lakh retail touchpoints, 57 C&F depots and 144 exclusive parlors. The company sells through general trade, modern trade, HoReCa, e-commerce, B2B and export channels. The company also owns its fleet with over 60 vans for procurement, along with 282 trucks for distribution of perishable goods and 34 trucks for distribution of non-perishable goods.
Key risks and concerns:
Concentrated Milk Procurement Network:
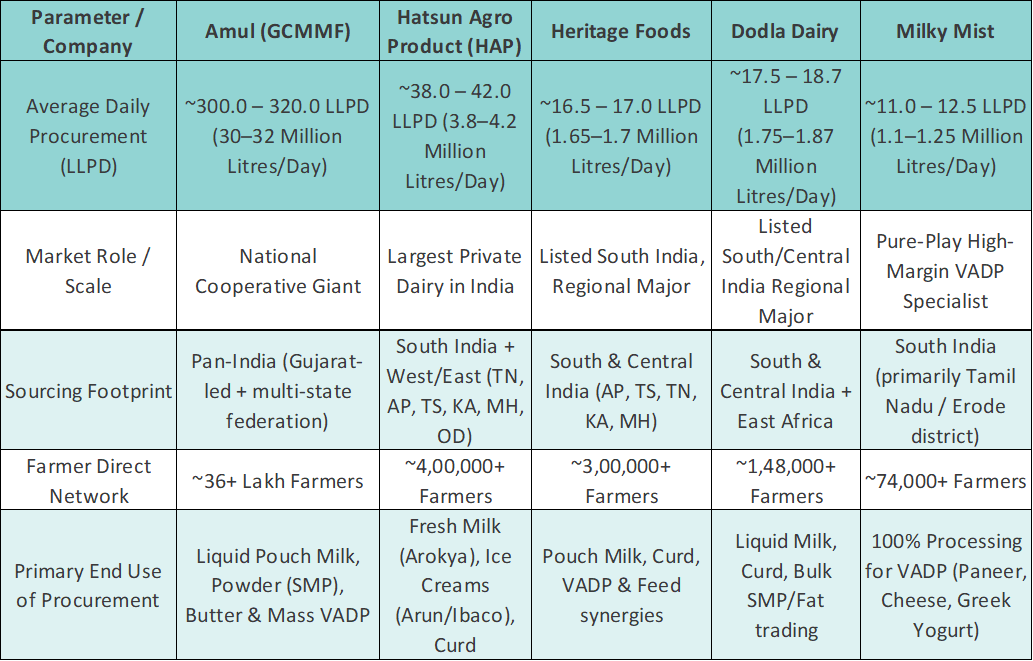
Milky Mist sources milk directly from over 74,000 dairy farmers primarily around Tamil Nadu. This exposes them to specific geographical risks despite its well-established procurement infrastructure comprising automated milk collection units and chilling centers. Most other players have a much wider procurement, usually banking on 2 or more geographical regions. The competitive intensity for milk procurement is also high in the Tamil Nadu region due to the presence of 4 large players, which impacts input costs.
Source: Table compiled using AI inputs. Data could be prone to error
Peer Comparison:
Milky Mist has differentiated itself by focusing on premium, value-added dairy products, whereas all other players make milk packets their core product.
Dodla Dairy and Heritage Foods primarily focus on milk and curd, while for fats, their primary product is ghee. Hatsun Agro Products is the leading player among the peers in ice creams through its established brand “Arun Ice Creams”. Hatsun has not focused on Paneer and Cheese.
Parag Milk is the closest peer to Milky Mist in terms of product focus. Our channel checks suggest Milky Mist has replaced “Go Cheese” and Go Panner across shelves in South India.
As outlined above, all the listed players have a relatively diversified procurement network relying on multiple states and supplying to multiple states. Milky Mist depends entirely on the Coimbatore, Tamil Nadu belt where it faces stiff competition from Dodla, Hatsun and the local society “Aavin”
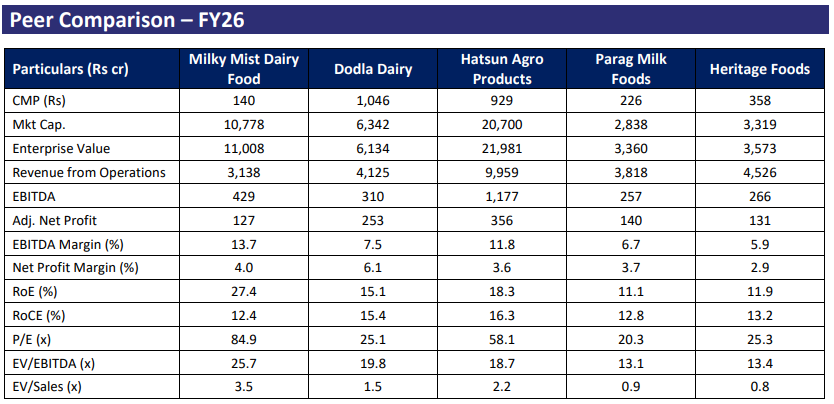
Based on financial performance, Milky Mist has been the fastest-growing player in the market with FY23-26 revenue CAGR of 30% vs 9-11% for peers.
Gross and operating margins are also higher relative to peers given the focus on value-added products.
However, the ROCE is the lowest among listed players, likely due to its heavy capex investments. Milky Mist has invested ~900cr in the last 4 years in aggressively adding capacity and supplying coolers for its distribution network.
Another outlier is Milky Mist’s debt-funded balance sheet; all dairy players operate on a net cash position. This will get normalised post IPO
Thoughts on IPO and valuation:
Clearly, Milky Mist is the best opportunity among listed players to play the growth of value-added dairy products in India. However, its positioning vs market leader “Amul” is yet to be properly tested as the company has only recently expanded into the north markets. This phase will be marked by aggressive investments not just in building distribution but also brand recognition.
While the mgt currently seems confident of its cold storage value chain to serve national markets from a solitary unit, such narratives will be tested by time and add to the concerns around free cash flow generation.
While Milky Mist should definitely trade at a premium to peers given its higher growth trajectory and expectations of stronger profitability. What investors will wait to see is whether this can translate to higher ROCEs as well. At the current juncture, its ROCE is materially weaker than for peers, questioning the premium narrative.
The deal is being priced at 85x FY26 PE, a sharp premium to the peer range of 20-50x, leading to our question: is there any cream left on the table for IPO investors?
Temasek’s backing could add some flavor to the stock. After acquiring ~6% stake in the company through the Pre-IPO, the fund is leading the anchor round as well, raising its stake above 7% post IPO.
This article provides a concise summary of my views on the Milky Mist IPO. For a comprehensive analysis covering the company’s business model, industry outlook, financial performance, valuation, key risks, and investment thesis, read my full research report on Smartkarma.
Read the detailed report using the link attached below.
Milky Mist IPO - Any Cream Left for Investors?. Read more: https://skr.ma/yH9W8
🤝Connect with us
Check out our services @ research.stylusholdings.com
Follow the Stylus Analytics channel on WhatsApp: https://whatsapp.com/channel/0029Va9E5GQBlHpbGfnn4L0WStylus Analytics
Subscribe to our YouTube Channel for insightful videos and detailed market analysis:
https://youtube.com/@stylus.holdings?si=J92dLCwupqqNt6mz
📸 Follow us on Instagram for quick market updates, reels, and educational content:
https://www.instagram.com/stylus.holdings utm_source=qr&igsh=MWZwc3BtdWx0dmFhaw==
Happy Investing!!!
Disclaimer:
Himanshu Dugar is a SEBI-registered research analyst (No. INH200009944). BSE Enlistment No. 5593
Content shared on this handle is for informational and educational purposes only and does not constitute personalized investment advice, recommendations, or solicitation to buy or sell any security. Investments in securities markets are subject to market risks. Please read all related documents carefully before investing.
Full statutory disclosures: stylusholdings.com/disclosures/