CAS Rules Under SEBI Review: What It Means for Traders and Investors
SEBI to Review CAS Settlement Rules: What Could Change for Traders?
Introduction
India's capital market has recently witnessed increased attention around the Closing Auction Session (CAS) and its impact on derivative settlement prices.
The Securities and Exchange Board of India (SEBI) has announced that it will review the methodology used to determine settlement prices of derivative contracts on expiry, following feedback received from market participants after the implementation of CAS in the equity cash segment.
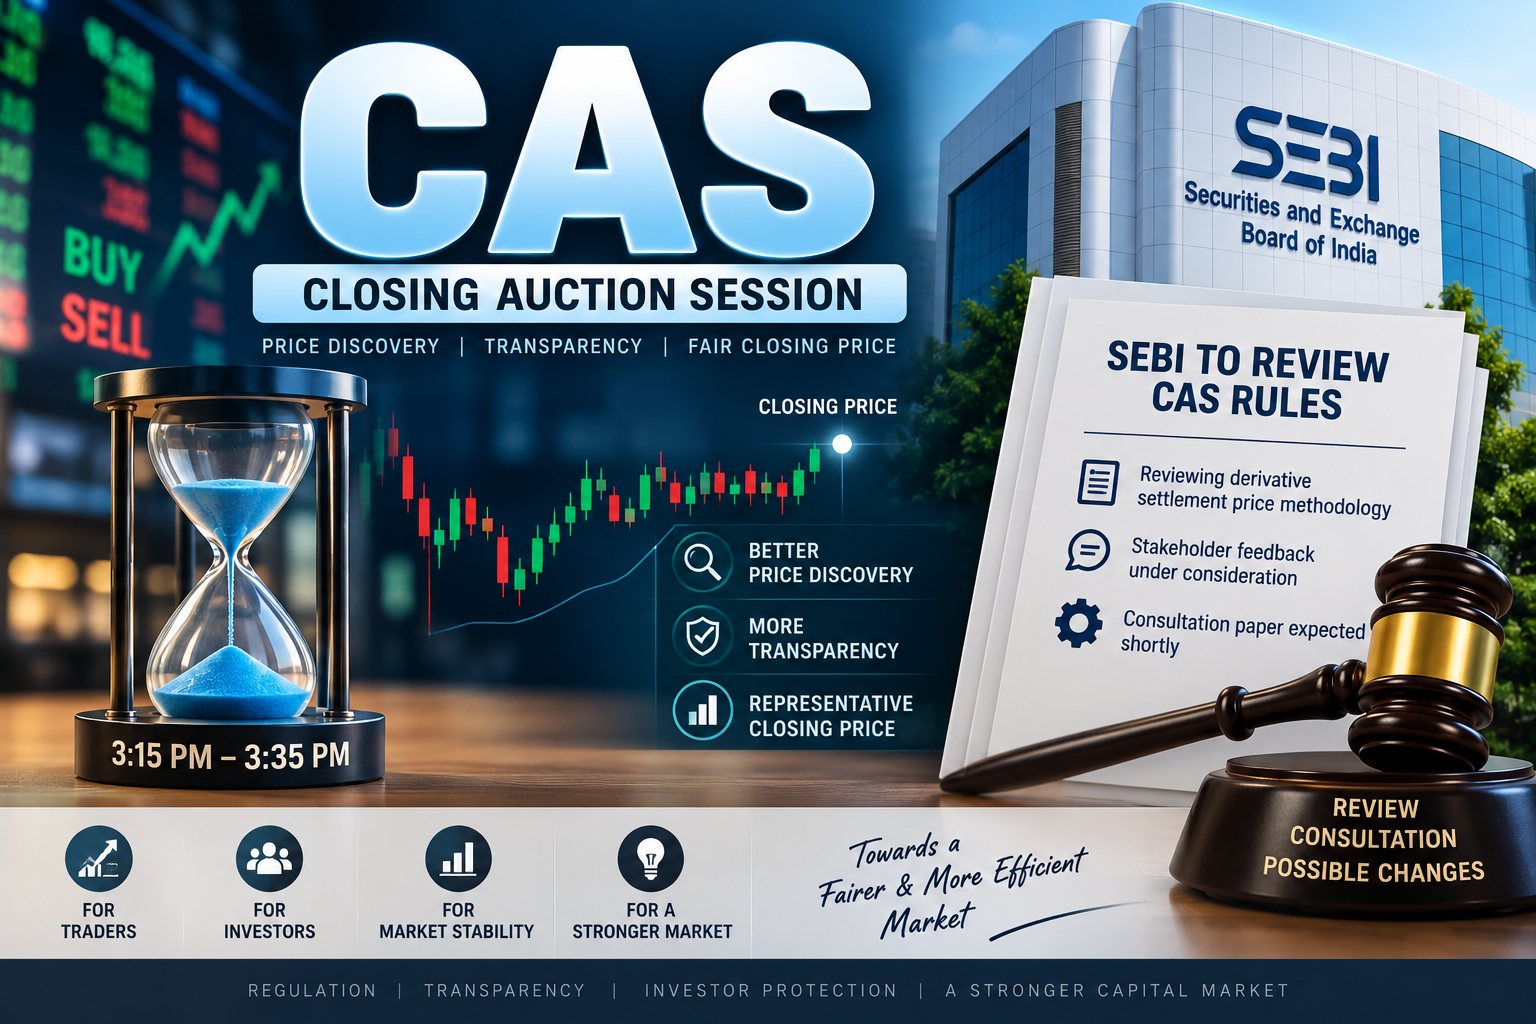
Importantly, the current development should not be interpreted as SEBI withdrawing the CAS mechanism. The review is primarily focused on the link between CAS-determined closing prices and derivative settlement prices. SEBI has indicated that a consultation paper on the proposed changes is expected shortly.
What is Closing Auction Session (CAS)?
The Closing Auction Session (CAS) is a dedicated auction mechanism introduced by SEBI for determining the closing price of eligible securities in the equity cash market.
CAS became effective from 3 August 2026. Before its introduction, the closing price of eligible stocks was determined using the Volume Weighted Average Price (VWAP) of trades executed during the last 30 minutes of the continuous trading session.
Under CAS, buy and sell orders are aggregated during a dedicated closing session and an equilibrium price is determined based on the maximum executable volume. The objective is to improve price discovery and provide a more transparent and representative closing price.
How Does the CAS Work?
Under the framework introduced by SEBI, CAS operates as a separate 20-minute session from 3:15 PM to 3:35 PM.
The session broadly consists of:
- Reference price calculation and transition from continuous trading
- Order entry for limit and market orders
- Order entry for limit orders
- Random closure of order entry
- Order matching and determination of the equilibrium price
The reference price for CAS is based on the VWAP of trades executed between 3:00 PM and 3:15 PM. A price band of ±3% from the reference price is applicable during CAS.
Why Has CAS Become a Topic of Debate?
The key issue is not simply the closing auction itself.
The major concern is the use of the CAS-determined closing price for settling derivative contracts on expiry.
Under the existing framework, the closing price determined through CAS also becomes the basis for determining the settlement price of relevant derivative contracts on expiry.
This creates a direct connection between the cash-market auction and the derivatives market.
On normal trading days, this mechanism may function without significant disruption. However, on expiry days, even a relatively sharp movement in the closing price can have a substantial impact on derivative positions, particularly options.
What Happened During the Recent Market Volatility?
The issue received greater attention after sharp movements were witnessed around the CAS on 3 September 2026.
During the closing auction, the indicative Sensex close briefly fell by around 2.5%, while premiums of some BSE Sensex put options reportedly surged sharply. The Sensex subsequently recovered and closed lower by about 0.55%.
Such movements raised concerns among market participants regarding the interaction between:
Cash Market Closing Price → CAS → Derivative Settlement Price
This has prompted greater scrutiny of how the closing price should be used for derivative settlement, particularly on expiry days.
What Exactly Is SEBI Reviewing?
According to SEBI's announcement, the regulator is reviewing the methodology for determining settlement prices of derivative contracts following feedback from stakeholders.
This distinction is important.
SEBI is not currently saying:
❌ CAS will be removed
❌ CAS will be suspended
❌ The previous VWAP system will definitely return
The current review is focused on:
✅ How derivative settlement prices are calculated
✅ The impact of CAS-derived closing prices on expiry settlements
✅ Market volatility around the closing auction
✅ Feedback received from market participants
✅ Whether changes are required in the existing settlement framework
SEBI has stated that it may propose changes to the methodology and plans to issue a consultation paper for further consideration.
Why Is Derivative Settlement Price So Important?
For derivative traders, the settlement price can directly influence the final value of positions on expiry.
Consider a simplified example.
Suppose a stock's price is trading around ₹1,000 during the regular market session.
If the CAS results in a significantly different closing price, that closing price can affect the settlement of the corresponding derivative contract.
For traders holding large futures or options positions, even a relatively small movement in the settlement price can result in a significant change in profit or loss.
Therefore, the methodology used to determine the final settlement price is particularly important on expiry days.
CAS vs Earlier Closing Price Method
| Earlier Framework | CAS Framework |
|---|---|
| Closing price based on VWAP | Closing price determined through auction |
| Last 30 minutes of continuous trading | Dedicated closing auction session |
| Continuous trading-based calculation | Order aggregation and price discovery |
| No separate closing auction | 20-minute CAS |
| Derivative settlement linked to closing price | Derivative settlement linked to CAS closing price under current framework |
The objective behind CAS was to create a more transparent and efficient mechanism for discovering the closing price. SEBI's original framework noted that a fair closing price is important because it can be used as a reference for derivative settlement, index computation and mutual fund NAV determination, among other purposes.
What Could Change Going Forward?
At this stage, it would be premature to predict the exact changes.
However, the upcoming SEBI consultation paper should provide greater clarity on whether the regulator proposes changes to the methodology used for derivative settlement.
Possible areas that market participants may closely watch include:
- Whether CAS closing prices continue to be used directly for derivative settlement
- Whether a separate methodology is considered for expiry-day settlement
- Whether additional safeguards are introduced around expiry
- How cash-market price discovery and derivative settlement can be better aligned
- Measures to reduce excessive volatility during the closing period
These are areas to watch rather than confirmed policy changes.
What Does This Mean for Traders?
For traders, especially those active in index and stock derivatives, the development is important because any change in settlement methodology can affect expiry-day trading strategies.
Until SEBI formally proposes and implements any changes, traders should continue to follow the existing exchange and regulatory framework.
It is also important to avoid making trading decisions purely on the expectation that CAS rules will be reversed.
The upcoming consultation paper will be a key document for understanding the regulator's proposed direction.
What Should Investors Watch Next?
The next major development will be the SEBI consultation paper on the proposed changes to derivative settlement-price methodology.
Market participants should closely monitor:
- SEBI's consultation paper
- Public comments and stakeholder responses
- Final SEBI decision
- NSE and BSE circulars
- Any changes to derivative settlement methodology
- Implementation date of any revised framework
Until a formal decision is announced, the existing CAS framework remains relevant.
Conclusion
The introduction of the Closing Auction Session represents a significant change in India's equity-market closing-price mechanism.
CAS was introduced with the objective of improving price discovery, transparency and efficiency in determining closing prices. However, its interaction with the derivatives market—particularly on expiry days—has generated feedback and concerns from market participants.
SEBI's latest move is therefore significant.
Rather than announcing the withdrawal of CAS, SEBI is currently examining how derivative settlement prices should be determined in the context of the CAS-generated closing price.
The upcoming consultation paper should provide greater clarity on the regulator's proposed approach.
For traders and investors, the key takeaway is simple:
CAS is under review, but the immediate focus is on derivative settlement methodology—not necessarily on removing the Closing Auction Session itself.
The final impact will become clearer once SEBI publishes its consultation paper and subsequently announces any changes to the existing framework.