
Zepto Attractive Valuation or Value Trap?
Zepto (Kiranakart Technologies Pvt. Ltd) has been preparing for an IPO for several months. The company last raised capital in September 2025 at a valuation equivalent to approximately ₹55/ share. Since then, it has continued to spend aggressively to gain market share, even as competitors such as Swiggy Instamart and Blinkit (under Eternal) have become more disciplined with their spending.
Today, the operational capabilities of the three major quick-commerce players are broadly comparable. Blinkit remains the market leader with an estimated 40–45% market share, while Zepto and Swiggy Instamart each command roughly 25–30%. However, competition is intensifying with the aggressive expansion of Flipkart Minutes and Amazon Now. The entry of these well-capitalized players has made investors increasingly cautious.
The key question is whether Zepto can continue burning cash while competing against companies backed by Amazon and Flipkart. Alternatively, will it be forced to adopt the more disciplined approach followed by Blinkit and Swiggy, focusing on operating leverage and allowing growth to become more organic? This uncertainty is a major reason why investors remain hesitant.
Recent reports suggest that Zepto’s investment bankers attempted a pre-IPO fundraise at approximately ₹19 /share but received limited investor interest. While the exact reasons are known only to the participants, investor caution is understandable given the prospect of a prolonged competitive battle involving some of the world’s largest technology companies.
Here's a breakdown of what's good, bad, and ugly in Zepto:
Good
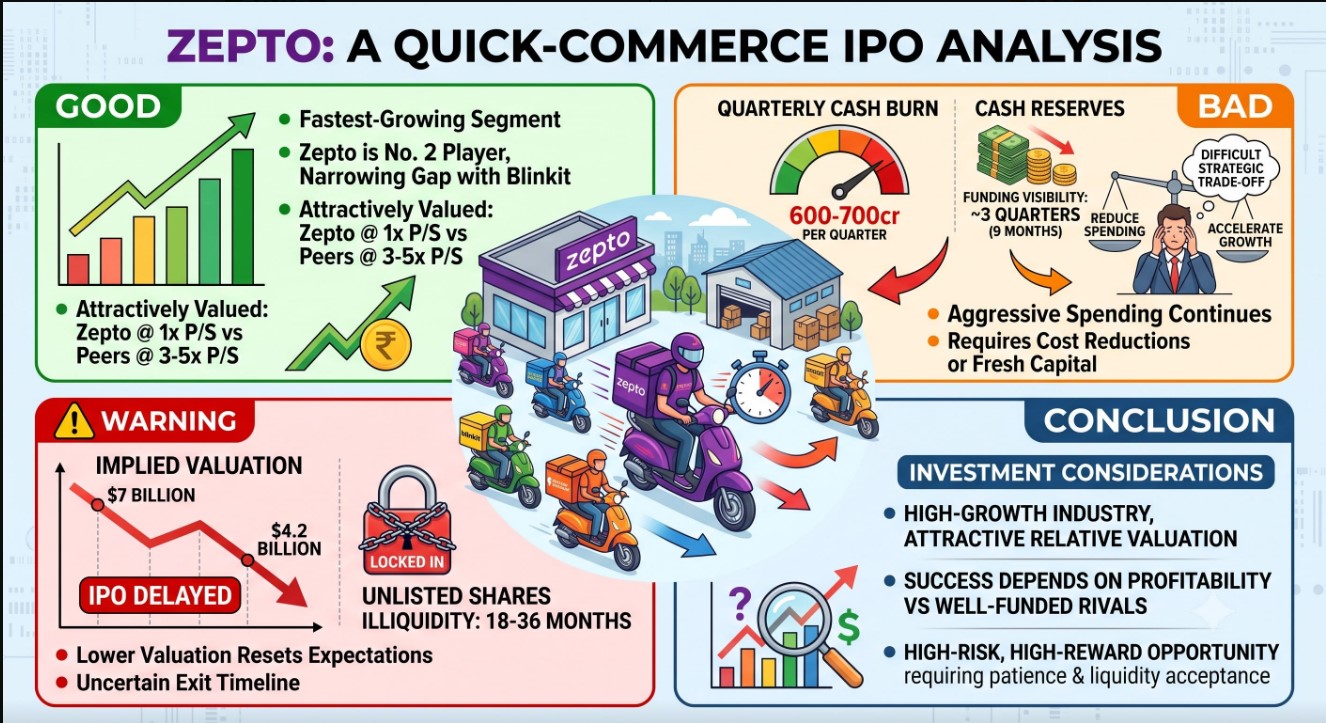
Quick commerce remains one of the fastest-growing segments of India’s consumer internet economy. Zepto is the No. 2 player in India’s highly competitive quick-commerce market and has steadily narrowed the gap with market leader Blinkit. At around ₹19/share, Zepto appears to trade at roughly 1x Price-to-Sales (P/S), whereas listed peers such as Swiggy and Blinkit (via Eternal) trade at approximately 3–5x P/S. If Zepto eventually achieves similar profitability and public-market valuation multiples, the current valuation could appear attractive.
Bad
Zepto is estimated to be burning approximately 600–700 cr per quarter. Assuming cash reserves of around 2,000 crore, the company has funding visibility of roughly three quarters (about nine months) without meaningful cost reductions or fresh capital. At the same time, reducing investments too aggressively could slow growth precisely when competition from Amazon and Flipkart is accelerating, creating a difficult strategic trade-off.
Ugly
The IPO has reportedly been delayed. The company is now exploring raising capital at an implied valuation of around $4.2 billion, substantially below the earlier private valuation of approximately $7 billion. If the public listing is delayed by another 18–36 months, investors in unlisted shares face significant illiquidity and an uncertain exit timeline. A lower fundraising valuation could also reset market expectations and put pressure on existing shareholders.
Conclusion
Zepto operates in a high-growth industry and appears attractively valued relative to listed peers. However, its success depends on improving profitability while competing against well-funded rivals. Investing in Zepto’s unlisted shares is a high-risk, high-reward opportunity that requires patience and acceptance of liquidity constraints and potential valuation changes.